Finding a financial advisor in Bangalore is easy.
Finding an unbiased one requires a little more work.
Search online and you will find wealth managers, financial planners, investment consultants, mutual fund distributors, insurance agents and investment advisers. To an investor, the differences between them aren’t always obvious.
For someone with substantial wealth, those differences matter.
You may have a business, real estate, direct equity, mutual funds, fixed income, ESOPs, insurance, overseas investments or alternative investments. You may also have a CA, lawyer, banker and other professionals advising you.
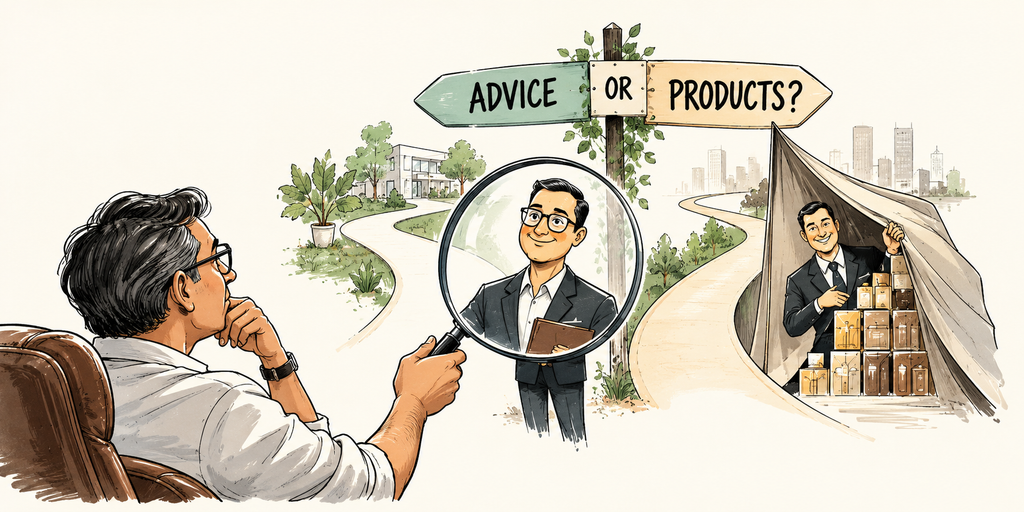
So the question isn’t just:
“Where should I invest?”
It is also:
“Who can look at my entire financial picture and advise me without being influenced by what they can sell me?”
That is where SEBI registration and the adviser’s compensation model become important.
Check the SEBI registration
Investment Advisers in India are regulated by the Securities and Exchange Board of India (SEBI).
If an individual or entity is providing investment advice for consideration, it needs to operate within the applicable SEBI Investment Adviser framework.
There is a difference between someone who calls themselves a financial advisor, wealth consultant or investment expert and someone who is actually registered with SEBI as an Investment Adviser.
Don’t rely on the title.
Check the registration.
SEBI maintains a public database of registered intermediaries, so you can verify it yourself.
How to verify an Investment Adviser
Go to the SEBI website and search under the Investment Adviser category:
SEBI Recognised Intermediaries
Check three things:
The legal name: The brand name may be different from the entity that holds the registration.
The registration number: Ask the adviser for it and verify it independently.
The entity details: Make sure the registration belongs to the person or company you are actually dealing with.
It takes only a few minutes. If you are entrusting someone with decisions involving several crores of rupees, it is a check worth making.
Adviser or distributor?
This distinction is often misunderstood.
A mutual fund distributor earns remuneration for distributing mutual fund products.
An insurance agent earns a commission from the insurance company for selling insurance products.
A SEBI-registered Investment Adviser charges the client a fee for providing investment advice.
Put simply:
Distributor → paid for distributing products.
Adviser → paid by the client for advice.
Neither model automatically makes someone good or bad.
The important thing is to understand the relationship.
If someone recommends an investment to you, ask:
“How are you compensated if I invest in this?”
It is a perfectly reasonable question.
What does fee-only mean?
A fee-only adviser is paid by the client for the advisory service rather than earning commissions from the financial products being recommended.
For someone with substantial wealth, the distinction can be meaningful. The larger the portfolio and the wider the range of products available, the more important it is to understand the incentives behind a recommendation.
A fee-only model doesn’t guarantee good advice. It does, however, remove one potential conflict—the adviser being financially rewarded for choosing one product over another.
Ask:
“Do you receive any commission, trail, referral fee or other remuneration from the products you recommend?”
You should know the answer before you engage the adviser.
Your portfolio may be diversified. Your wealth may not be.
This is something wealthy investors often overlook.
You may have mutual funds, direct equity, real estate, bonds, an AIF, PMS and international investments.
On paper, it looks diversified.
But suppose your business, real estate and investments are all heavily exposed to the same sector, geography or economic cycle.
You could own 20 different investments and still be carrying one large underlying risk.
That’s why looking at products individually isn’t enough.
The better question is:
“What risks am I already carrying across my entire financial life?”
More products don’t necessarily mean better advice
As wealth increases, the menu gets bigger.
AIFs.
PMS.
Private credit.
Structured products.
SIFs.
International investments.
Alternative strategies.
Many of these products can have a legitimate role.
But the product shouldn’t be the starting point.
The starting point should be your objectives, liquidity needs, risk capacity, existing exposure and overall asset allocation.
Only then should you decide whether a particular product belongs in the portfolio.
Otherwise, it is easy to end up with a collection of interesting investments rather than a coherent investment strategy.
Look at the whole financial picture
For a wealthy family, investments are only one part of the picture.
There may be a business, property, ESOPs, direct equity, financial investments, insurance, overseas assets and family-owned assets.
There may also be several professionals involved—a CA, lawyer, banker, insurance professional and investment adviser.
Each may be doing a good job within their own area.
But someone still needs to see how the pieces fit together.
Does the investment portfolio add to the concentration already present in the business?
Is there enough liquidity outside the business and real estate?
How much investment risk is actually necessary to achieve the family’s goals?
What happens when the business is sold or passed on to the next generation?
These aren’t product questions.
They are wealth-management questions.
What about myMoneySage?
myMoneySage is one example of a fee-only, SEBI-registered Investment Adviser.
The advisory business operates through Shreem Datatech Solutions Private Limited, with SEBI Investment Adviser registration number INA200014247.
We mention this simply so that readers can verify the same information they should verify about any adviser.
Check the registration.
Understand the fee structure.
Ask about commissions and other remuneration.
Understand what the adviser is actually responsible for.
Then decide whether the relationship is right for you.
Five questions worth asking
Before choosing an adviser, ask:
1. Are you registered with SEBI as an Investment Adviser?
Ask for the registration number and verify it yourself.
2. How are you compensated?
Understand the complete fee structure.
3. Do you receive commissions, trails or other remuneration from the products you recommend?
Don’t assume. Ask.
4. Are you advising on my overall financial situation or primarily recommending products?
There is a significant difference.
5. What would you tell me not to invest in?
The answer can be revealing.
Anyone can show you what they recommend.
A good adviser should also be able to explain what they would not recommend—and why.
Choosing an adviser
The more wealth you accumulate, the more investment choices you will encounter.
That doesn’t necessarily make investing easier.
It can actually make it harder to see the bigger picture.
The value of an adviser isn’t simply in finding another investment.
It can be in identifying risks you already have, avoiding unnecessary complexity, keeping the portfolio aligned with your objectives and, occasionally, telling you not to invest.
Because when you have substantial wealth, the biggest question isn’t always:
“What should I invest in?”
Sometimes it is:
“Who is looking at everything I already own—and is that person truly advising me, or selling me something?”
That is a very good question to ask before choosing a financial advisor, whether in Bangalore or anywhere else.
Investors are advised to consult their financial advisors before making any investment decisions. This view does not constitute investment advice.
If you do not have one visit mymoneysage.in
